CooperAitken Admin

Keeping the cash flowing into your business

Our business environment has been challenging for some time, and it is likely to continue in the near future. There are pressures with rising costs from suppliers, wage costs increasing, and an inability to attract new employees, just to name a few. Being an election year business owners have elevated levels of uncertainty with potential changes to policies that affect their livelihoods, family, and their staff.  There are many external factors that we cannot control such as rising interest rates, inflation, and a tight labour market. So, let’s focus on looking inward at our own businesses and see what we can improve to alleviate some of this pressure.  This article looks at ways to improve cash flow into your business from customers, focusing on your accounts receivable and reducing the time it takes for you to get paid. Reassess your customer payment terms Many commercial businesses follow conventional payment terms of payment being due by the 20th of the month following the invoice date.  Traditionally invoices would be sent by post at the end of the month with the due date being the 20th of the month, this gave people enough time to post their payment by cheque to their suppliers.  Technological advancement has seen invoicing processing time shrink considerably so you could look to reduce the payment terms to 14 or even 7 days following invoice date.  In terms of money entering your bank account how much would this change impact your cashflow? An example of how this benefits your cash flow is if you completed a job on the 4th of the month and billed it to your customer by the 6th of the month you could expect payment on the 20th that same month, this shows a cash conversion cycle of 16 days. If you kept the status quo then you could be waiting for payment until the 20th of the month following, this adds 31 days until you are paid for work completed.    If your bank balance is currently in overdraft then you are effectively paying the bank interest while you wait for customers to pay you. Would you be happy to discount your customer’s bill by the current interest rates being charged, say 15%?  In a way you are wearing the 15% interest cost of these credit terms.  In order for you to be able to achieve this potential cash benefit you would have to ensure your team has the capacity to generate an invoice promptly following the sale or completion of work.  If not, then perhaps a streamlined invoicing process is another key area of focus to consider.  Give customers ease with payment options These days there are many options for securing payment from customers.  Most people have access to Internet banking apps on their phones and can pay bills from anywhere and at any time.  The major banks now process money transfers seven days a week. This is good news for everyone as cash is flowing quicker than ever before. Put yourself in the place of your customer – what options are there for paying your business? Do you offer multiple payment methods? Here are some common ones to consider: Online banking – provide bank account number on your invoice or statement and the customer can pay at any time that suits them. Payment by eftpos or credit card – either at your business premises or mobile Direct debit – great for ensuring payment is received on time. Online – include links on your invoice to a payment service provider to process credit card payment or offer POLi for direct bank transfer Website – add a ‘pay now’ function on your website Cash – if you receive cash it is best practice to provide a receipt to your customer either electronically or from a carbon copy receipt book.  The goal is to make it convenient and easy for customers to pay. Asking for a deposit for sales where you agree on the price prior to starting the work is a great way to help with cashflow. The above-listed payment methods are not without risk or cost. Credit card and Paywave attract merchant and bank fees and a cash handling fee can be charged when depositing cash. In the world in which we operate, this is a cost of operating a business. Choose the options that you prefer once considering the cost and risks of each method. Talk to your customer There are  tools available to remind customers to pay their account such as end-of-month statements, automated invoice reminders, and charging late payment fees or interest to overdue accounts. These are often effective methods to trigger a payment response from customers.  When these tools are not enough it is important to phone and talk to your customer. Often a few minutes talking to your customer will result in action from them. Take a proactive and empathic approach to this.  It can be easier to ignore automated statement reminders whereas by talking with a customer you can help clear up issues. If you are willing to agree to a payment plan this can be preferable to the non-payment alternative. Note with payment plans there is a delay in when you receive payment, therefore you may wish to add interest to a payment plan to account for this delay. Getting paid on time is one important part of improving your cash inflows. Having money coming in when it is expected helps alleviate pressure and helps with your ability to pay your bills when they are due. Set aside time to regularly review your accounts receivable and be proactive with overdue accounts. Challenge yourself to put some time into assessing what changes you could make to improve the time between sale and payment. We want you to get paid for your hard work and effort. Please reach out to us if you want a sounding board or further advice on how to improve your current payment terms or methods.  Eddie Maber, Accountant.   Returns to

Keeping the cash flowing into your business Read More »
Let’s talk about bonuses!

You might be considering offering some kind of incentive or bonus for your staff. It’s important to be aware that there are two types of bonuses an employer can give, an incentive payment or a discretionary bonus, and they are quite different. An incentive payment is generally paid on a regular basis if X Y & Z criteria are met. This criteria is outlined and agreed upon in the individual employment agreement. It is a set amount and is agreed upon in the contract with the employee. If the criteria outlined are met, then the employer must make this payment. However, a discretionary bonus is paid at the sole discretion of the employer. They are generally also performance-based, but the main difference is that it is not considered part of the employee’s regular pay and does not make up their total package. The employer can change the amount of this bonus at any time or not make a payment at all. Tax on bonuses also differs depending on what type you are paying. An incentive payment that is paid on a regular basis is taxed according to the employee’s tax code as this is considered part of their salary package. To work out the correct amount of tax on a discretionary bonus we need to apply the lump sum taxation method as this payment is above and beyond their normal wage. When selecting which type of bonus to pay your staff, it is also important to keep in mind the effect it has on holiday pay. As an incentive payment is part of the employee’s regular pay it gets included in their calculation for the average daily rate or relevant daily pay, therefore it bumps up the hourly rate that is required to be paid on holiday pay. In contrast, the discretionary bonus is not considered with these calculations as it is not part of their regular income. Our advice on bonuses is that you need to be very clear on what type you are paying and the effect it will have on your business. Have very specific parameters for the bonus, e.g. If you reach your sale target of $2,000 per month for the sales quarter of January to March, an incentive payment of $200 will be paid on the 20th of April. Or, A discretionary bonus of $500 might be paid to the employee for a Christmas bonus in December depending on the employee’s performance. As this is a discretionary bonus the employer can decide to change the amount, payment date or not make the payment at all. Ensure your employee understands if it is an incentive payment or a discretionary bonus and what that means to them. Bonuses can be a great way to incentivise your existing employees or recruit new ones. The trick is for the employer and the employee both to understand exactly what criteria need to be met for a payment to be made, how the payment will be taxed and if the bonus is discretionary or not. Here’s a quick breakdown of the differences; Incentive Payment Discretionary Bonus Calculated at normal PAYE Rates Calculated on Lump Sum Taxation Is a pre agreed amount that must be paid Is a discretionary amount that can be paid Is part of the whole salary package Is in addition to the salary Affects the holiday pay rates Does not affect holiday pay rates It is always a good idea to get expert advise that is tailored to your specific business and at CooperAitken we are more than happy to help. Anna Hollingsworth, Payroll Administrator Contact our Payroll Team:P: 07 889 7153E: wages@cooperaitken.co.nz Returns to blogs

Let’s talk about bonuses! Read More »

June 2023

INCLUDED THIS MONTH; New article from Rory Noorland: The Principles of Tax Gavin’s retirement from Awarua Trust Agri-businesses: Have you counted your stock? Coming up: Xero Tips & Tricks Coming up: Payroll drop-in sessions download here Returns to blogs

June 2023 Read More »

The Principles of Tax

The Taxation Principles Reporting Bill was recently introduced to Parliament stating that “The Government would like to increase the public’s understanding of the tax system and promote informed debate and discussion about its future”.   The Bill proposes 7 principles that are to be “universally accepted” as underpinning the design of good tax policy.  The principles identified are: horizontal and vertical equity; efficiency; revenue integrity; certainty and predictability; flexibility and adaptability; and compliance and administration costs.   This Bill comes off the back of 3 years of highly complicated and, at times, ad hoc changes to the tax settings that has occurred in the last 15 years.  The goal of efficiency is that “Tax revenue should be raised in ways that minimise distortions to the economy and the use of resources” whereas certainty and predictability aims that “People should be able to determine their tax obligations before they are due”. Though being at the theoretical end of tax legislation, had these principles been applied earlier we could have avoided the situation of having the ever increasingly complicated Bright-Line test rules and avoided the distortionary limitation of interest deductions on residential rental properties. The interest limitation rules for residential rental properties is one of the most unnecessary and complicated changes to the taxation system seen in a long time.  Had the 7 tax principles ruler been run across this legislation at the time it would have surely failed almost all of them.  The rules are proving to be distortionary and producing an outcome where an arbitrary date determines whether a property is able to have interest deductions for a period of 20 years or no interest deduction at all. It is the worst example of using the taxation system to attempt to fix a non-tax issue without regard for the distortions and complexity it creates for taxpayers.  It also opens the ability for the bigger and more well-resourced taxpayers to lobby for exemptions such as build-to-rent developers. There is no equity to giving larger landlords the ability to access an interest deduction due to scale vs the mum and dad investor who now cannot.  The 10-year (or 5-year if it is a new build) Bright-Line test is another example of the difficulty that taxpayers have in understanding their tax obligations without the assistance of tax professionals. Remembering that the principle of certainty and predictability means that taxpayers should be able to determine their tax obligations before they are due.  Some of the recent tax policy decisions that have been made has resulted in a highly complicated and ever increasingly difficult set of tax rules for the everyday taxpayer to navigate.  All too often taxpayers are caught out with a nasty surprise after they have sold the property, filed their tax return and merrily gone on with their lives. Often this is as a result of an accident rather than an attempt to derive income from property transactions, whether it is the misapplication of the main home exemption, of which there are now also different tests depending on when the property was purchased, through to change of circumstance situations for which there is no leniency. Brightline began with an aim of taxing property speculators who ‘flipped’ houses for a living. Now we see an ever-increasing list of exemptions and roll over relief provisions necessary to ensure negative tax consequences can be avoided.  This is a prime example of a set of rules are now far overreaching beyond their initial aim. There is very little flexibility in these rules, by design, which is resulting in tax outcomes not originally intended by the legislation. We can only hope that the principles within this piece of legislation result in more rational and logical tax rules and that future governments both apply it to the tax policy they set and engage in a process of removing some of these unnecessary and at times punitive tax burdens that we have seen appear.  And finally, remember, “The hardest thing in the world to understand is the income tax” – Albert Einstein. Rory Noorland,Partner, CA P: 0800 866 191E: rory@cooperaitken.co.nzM: 021 721 368 More on rory Returns to blogs

The Principles of Tax Read More »

GST invoicing & record keeping changes: What are they & what do you they mean for you?

In March 2022, the government announced changes to the GST invoicing and record-keeping requirements, however, this was not enacted until 1 April 2023. These new rules have been introduced to allow for more flexibility around GST invoicing and record-keeping. GST rules have been largely unchanged since the inception of GST in 1986, which does not align with today’s business world as there have been significant changes to technology and the way business is conducted. The requirement to hold the “tax invoice” in order to be able to claim GST on that item has been replaced with holding business records instead, and the responsibility now falls both on suppliers and customers. Under the new rules, you can continue to issue your tax invoices and GST credit notes without making too many changes to your systems. The low-value threshold is lifting from $50 to $200, meaning that taxable supply information is required for any supplies over $200 rather than $50. There is no longer a requirement for approval from Inland Revenue for the issue of Buyer-created tax invoices (buyer-created taxable supply information). This has been replaced with an agreement in writing between the parties to evidence the use of self-billing. It is important to understand the terminology changes: “Tax invoices” are now referred to as “Taxable Supply Information (TSI)” “Debit Notes” and “Credit Notes” become “Supply Correct Information (SCI)” “Buyer Created Invoices” become “Buyer Created Taxable Supply Information” “Supply Information” is the list of information required on certain situations when the supply is not subject to GST Even though you may not be required to make any changes, it is still important to know about them as your suppliers’ invoicing practices may be changing and this could impact the way you conduct your business. Some things to be aware of are: You can continue to issue “tax invoices”, “debit notes” and “credit notes” if you wish. Check that your templates include the correct GST information. You do not need to provide the TSI if the customer is not registered for GST or the amount charged is under $200 (incl GST). TSI must be provided to GST registered buyers within 28 days of a request for supplies over $200. You must keep this information on file. Instead of issuing any of the above documents, you can provide a list of information (TSI) in a format chosen by you – in an email, electronic invoice, or an exchange of data with your customer or supplier via an e-invoicing system. You are not required to use or include the words “taxable supply information” in any document you provide as part of the TSI. You don’t need to issue a SCI of the error in the TSI if it has no GST impact. You can claim GST on a payment you make to your supplier and the TSI is required from your supplier in their selected format instead of a “tax invoice”. The TSI does not need to be received in the one document or format. It can be received in multiple formats and is up to the supplier on how this is done. Are your systems capable? With these changes, it can have a large effect your business systems and it is a good opportunity for you to review your system’s capabilities to ensure you can send/receive and hold TSI. Here are some questions to ask yourself: Do you need a supporting system alongside your accounting system such as invoice scanning software? This software generally checks the parameters to accept/reject invoices – for example, looking for the words “tax invoice” Do you need to consider your system’s abilities in relation to employee reimbursements, credit card reconciliations and the wider finance system to process TSI and the increases to the low-value threshold Do you have a customer and supplier database that is able to hold key information such as IRD numbers and addresses? Are your systems ready to move forward towards potential e-invoicing? How can you capture the approval from other parties to issue buyer-created taxable supply information? Are your finance staff educated on the new taxable supply requirements? Do your internal policies and procedures need to be reviewed in this area? Are your general terms of trade aligned with these changes? See below a chart that shows the changes in rules from 1 April 2023.   Paperless Systems: With the above changes in effect, it is a good opportunity to consider converting to a paperless system. This can increase the efficiency of your organization as well as create some time and mind freedom within your business. Although it can be unrealistic to eliminate every sheet of paper from your office, we can help you take the right steps toward this. You will need to ensure you have a good-quality scanner and an online filing system (such as Hubdoc) available for storage. Advantages of a paperless system: Storage – up to 25% of your firm’s office space could be used for the storage of paper documents. This is a big overhead, which may be holding you back from other things like taking on more employees. Time freedom and increase in productivity – It can be hard and very time consuming to find the right piece of paper amongst a pile with thousands of others. An online filing system with a powerful search function will reduce the time spent looking for documents and increase staff productivity. Waste – There may be duplicate copies of these documents and they may be filed in different places for different reasons. Going paperless will reduce this duplication and essentially reduce the waste as well – the paperless system is environmentally friendly. Appearance – Your office will be more aesthetically pleasing with less clutter as there will not be piles of paper and files throughout your office. The office will appear more like a professional working environment and will be more inviting to visitors, employees and clients. Mind freedom and more focus – Without a desk covered in paper, employees with

GST invoicing & record keeping changes: What are they & what do you they mean for you? Read More »

May 2023

INCLUDED THIS MONTH; New article from Sharlotte McFarlane: GST Invoicing & record keeping changes Directors Annual Strategic Retreat in Cambridge From our payroll division: Annual leave can be a contentious subject Provisional Tax Calculations Paying your invoice via internet banking Payroll drop-in sessions: Come in with your payroll queries  download here

May 2023 Read More »

Annual Leave can be a contentious subject

Firstly, it is important to understand that all Annual leave is the property of the employee, not the employer. Annual leave is accrued at 8% of the employee’s gross pay and after 12 months of continuous employment becomes entitled leave. An employee can request to use their accrued balance prior to the 12-month mark when it becomes entitled leave. However, it is up to the employer if they want to approve this leave in advance. Pros: Keep business liability down. Employees has access to sufficient rest and recreation, reducing risk of harm. Useful tool for nurturing a harmonious employment relationship. Cons: As accruing leave is not exact, there can be a risk of running into negative balances. Sometimes when the employer goes out of their way to assist the employee by providing annual holidays in advance, they turn around and decide not to come back or leave prior to reaching 12 months of continuous employment. While there are avenues within the Wages Protection Act 1983 to deduct annual leave in advance overpayments from the final pay, it can be very beneficial to have an accruing leave balance policy built into the Individual Employment Agreements (IEA) to outline exactly how an employee can take this accrued leave and keep it consistent between all staff. Managing excessive annual leave balances can be slightly trickier. As entitled annual leave is a liability, it is good practice to review balances regularly, to avoid this getting to high. It is always good to have clear lines of communication with your employees around their leave. Are they saving it up for a longer holiday further down the track? Is it too hard to take leave due to X Y Z? Would cashing up a weeks’ worth of their entitlement be a good option? An employer can make their employees take their entitled annual leave in two circumstances: They can’t reach an agreement with their employee about when annual leave will be taken, and they give the employee at least 14 days’ notice, or They regularly close down for a certain period every year and give the employee at least 14 days’ notice. When cashing in a week’s annual leave there are a few important things to keep in mind: The request to cash up annual leave must be made in writing. It will be taxed as a lump sum payment rather than regular income You can only cash in a maximum of 1 week of entitled leave each year (based on your annual leave anniversary) When annual leave is cashed up and paid out as a lump sum, the normal PAYE rates don’t apply. Instead, it is taxed as a lump sum payment. To work this out, you need to calculate the total earnings for the last 4 weeks ending on the date of the lump sum payment. Multiply this number by 13 to calculate the grossed up annual income value.   This value is then used in the below table to work out the tax of the lump sum. As an example, Mr Smith is cashing in 1 week of annual leave. He works a 40-hour week on a salary of $68,000 gross p/a. He uses the tax code M, contributes 3% to his Kiwisaver and has no other allowances or deductions. So, his normal weekly pay would be:$1,307.69 Gross$278.07 in PAYE$39.23 Kiwisaver$990.39 Nett If he were to cash up a week of annual leave, in addition to his regular salary payment, it would attract lump sum PAYE on the cash up amount, at 31.53%. See below; $1,307.69 Gross ordinary wages$1,307.69 Gross AL cash up (one week)$278.08 regular PAYE deduction$412.31 lump sum PAYE deduction (31.53%)$78.46 Kiwisaver$1,846.53 Nett            In conclusion, a well-managed annual leave account can benefit both sides of the employment relationship. At CooperAitken, our Payroll division can assist you to form good, solid leave balance management habits. Please call the team for further information. get in touch with our payroll team

Annual Leave can be a contentious subject Read More »

Costs, costs, costs.

Everywhere you look costs are increasing at an alarming rate and it is taking its toll on businesses and individuals alike. There are whispers of a recession which seems quite likely looking at the latest inflation numbers pegged at a staggering 7.2% for the 12 months to December 2022, which is the highest it has been since 1988. As a result of the high inflation in recent times, no business or individual has managed to escape the clutches of a price increase whether the increase is from a supplier or your weekly supermarket shop. Economists are saying that they believe inflation may have peaked, but that remains to be seen. For the purposes of this article, we will focus on cost pressures experienced by dairy farms at present which include not only price increases but also a drop in payout and a decrease in demand for dairy products which exacerbates the cost pressures. On-farm costs increasing As mentioned above there are cost increases across the board which are putting a squeeze on farmers’ profitability, the main ones of concern are: Interest rates on bank loans especially where farmers have high debt levels – interest rates are on the rise and are now more than double what it was 18 months ago which brings with it higher debt servicing costs on top of most banks requirements to repay the debt over 20 years. Limited access to staffing and the associated remuneration expectations Increase in major farm expenses such as fuel and fertiliser Costs related to compliance requirements, regulatory changes, and environmental requirements After a long hiatus we revived our Waikato Dairy Farming Benchmarking reports, the reports have been collated by our team from actual cash trading date of our Dairy Farming. The data we have collected for the 2021/2022 season reflect the items mentioned above. We have stats for: Farm Owner/Operators Farm Owner with 50/50 Sharemilkers 50/50 Sharemilkers Farm Owner with Contact Milker We have the ability to benchmark your farming operation against these stats which will allow you to see the areas of your business which are out performing others and those where you can make changes to increase your profitability, we believe that this is a very useful tool. Link to our website to look at the stats can be found here. Things dairy farmers can do to mitigate costs Farmers are paying close attention to their farming operations and where they can potentially gain some efficiency or cut costs items they are looking at includes: Changing twice a day milking to once a day milking therefore reducing labour input in as a response to potential staff shortages and or labour costs. Frequent actual variance reporting on the farm budget to ensure that areas of concern can be identified so it can be addressed. Potential energy costs savings by converting to solar power – some banks are providing “Green Loans” at favorable interest rates to enable such conversions. Consider ordering bulk amounts of supplies or stock to keep you going for a longer period of time and avoid price increased, of course there is a risk here of a potential price decrease after a bulk order, but is likely that once the cost goes up, it stays up. Speak to us and speak to your bank manager about the financial needs of your farm, for example interest rates/fixed terms or interest only options if available. In summary it is not all doom and gloom, the New Zealand dairy industry makes a significant contribution to New Zealand’s GDP and farmers are undoubtedly the backbone of New Zealand. We are here to help you create freedom in your business and please do not hesitate to contact us if we can help you with your farming budgets and variance reporting for the 2023/2024 season and beyond. Gerrie Jacobs,Partner, CA P: 07 889 7153E: gerrie@cooperaitken.co.nzM: 021 284 6444 More on Gerrie

Costs, costs, costs. Read More »

Increases are on the way: What are they & how to prepare

The Minimum wage is increasing Many of you would have heard and seen the announcement, that the minimum wage is set to increase 1st April 2023. The Adult minimum wage will go up, from $21.20 to $22.70 per hour. The starting out, and training minimum wage will increase, from $16.96 to $18.16 per hour. These rates are before tax and lawful deductions. It does not include 8% Holiday pay for casuals. This needs to be calculated on top. If you have salaried employees, you must ensure that your team are not at risk of falling below the new minimum wage, should they work additional hours. You will need to revisit your calculation for the maximum number of hours each can work, per pay period, before requiring a top up payment. The minimum wage is not the only change. The ACC Earner Levy is increasing In addition to the increase in minimum wage, the ACC Earner levy, which makes up part of your employees PAYE calculation, will also be increasing. This is a planned increase and is not in response to recent events. The planned increase from 1st April 2023 is from 1.46% to 1.53%, or, $1.53 per $100.00 of earnings. This will impact of the amount of PAYE paid to the IRD, for each employee. It is important that any salaried staff have their existing calculations revisited, to ensure the increase is accounted for. Student loan repayment thresholds are increasing The amount of money an employee can earn before the 12% Student loan is deducted, will increase from $21,268 to $22,828. On average, employees can expect to earn an additional $30 a week on their gross incomes, before the 12% Student loan deduction applies. Please see the table below for details. How to prepare for the increases 1. Advise your team If you have employees on the minimum wage, let them know about the increase they will be getting. You should send them a letter or email (variation of employment contract) advising them of the new wage. 2. Check your payroll systems and processesTalk to whoever runs your payroll system: your payroll provider, accountant, lawyer, and HR or finance people to make sure they are ready to implement the change. If your system is manual or computer-based you should check and confirm the settings will be adjusted for the new rates. If any of your employees are on starting-out or training wages, now is a good time to check when they will be eligible to move onto the adult rate. 3.  Employee pay relativity You may also wish to consider potential impacts on your business due to internal wage relativity (for example, how employees are paid compared to each other) and external benchmarking (such as how your pay rates compare to others in your industry or sector). Employees on higher wages may possibly want to negotiate a pay increase to keep the relative difference. Cooper Aitken Payroll Division understand that change can be stressful, and updating wage and salary calculations may not sit high on the list of priorities for 1st April 2023. Our services are not limited to existing payroll clients. We can also assist clients that process wages in-house, by preparing a comprehensive wage and salary calculation that clearly outlines the changes for your staff, and you can proceed with updating your employee records with confidence. Give our friendly team a call on (07) 889 7153, or send us an email at wages@cooperaitken.co.nz

Increases are on the way: What are they & how to prepare Read More »

An evening with John Kirwan

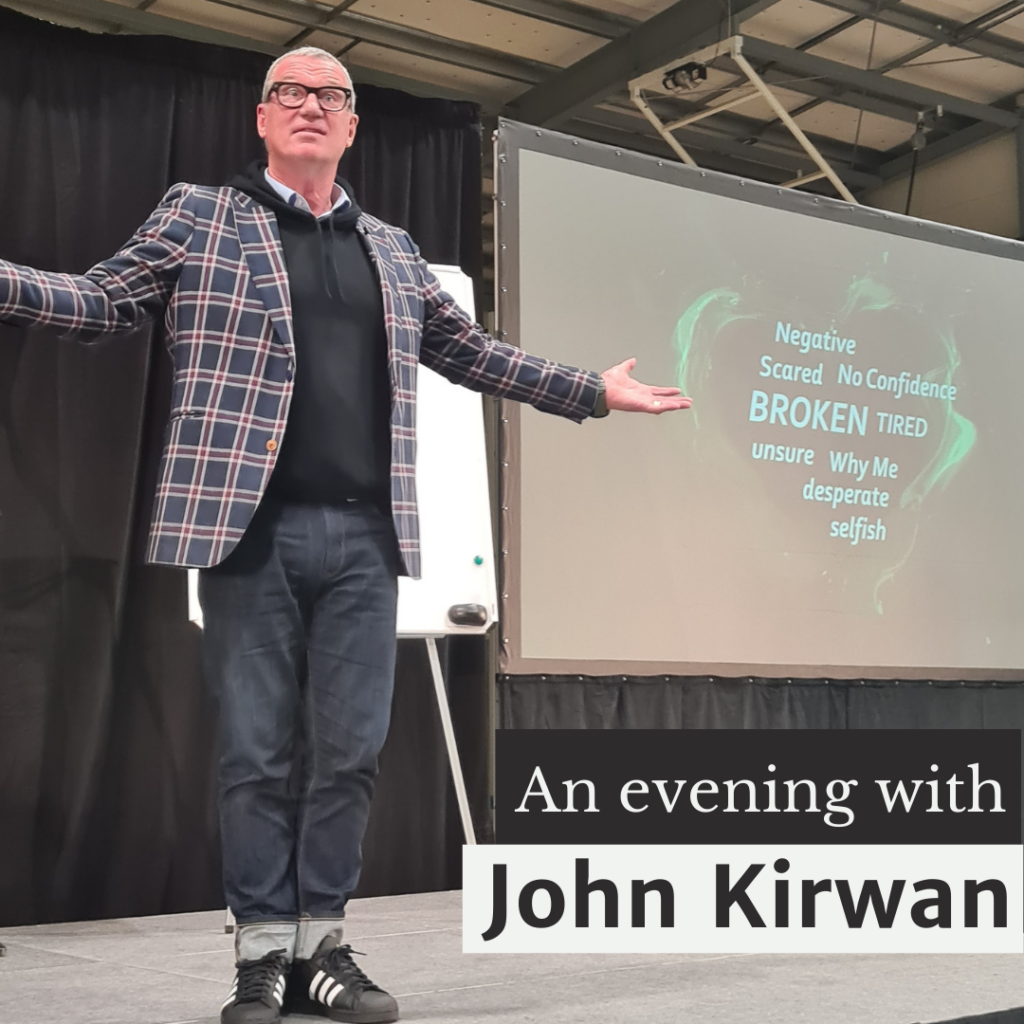
Over 500 people gathered in Te Aroha last month to listen to Sir John Kirwan, or JK as he’s most commonly known, share his humble yet powerful words on managing mental health and the process of moving from surviving to thriving.  It was an important message for rural communities. Across the country there is a common theme emerging of people on farms who, over the past few years, have persevered through challenge upon challenge. Over time, this feeling of facing a battle on many fronts takes a toll. The result is once lively people looking weary, worn down and having lost their spark. This was apparent to Theresa Tomkinson and Rex Madden, who work together at PGG Wrightson Tatuanui.   Theresa has an eye for spotting when things are off with someone. As the saying goes, it takes one to know one. Recently Theresa has experienced the loss of her brother in December last year and dealt with her dog being run over. She also experienced a reaction to a COVID vaccine and had to deal with the stress of COVID vaccine mandates earlier in the year. As a result of all this Theresa had started having panic attacks. She knew she wasn’t okay and decided to have a chat to Rex, Store Manager at PGG Tatuanui.  While many well-meaning managers can inadvertently foster a culture of productivity first, people second, Rex is a bit different. As Theresa explains. “Rex is really open. It’s really good to have a boss you can talk to when things build up”. Thoughtfully, she adds “But the relationship needs to be there to start with. Bosses need to be approachable, and you need to know that they care.” Having reached out, and with Rex’s support at work, Theresa tried some different avenues and eventually found the professional assistance she needed.   Over the next few months Theresa’s wellbeing returned, but she started noticing the wellbeing of customers coming in. Farmers who had gone through drought and other challenges, who, while normally very happy, were not ok.  She says, “We’re a retail store, but it’s a different kind of relationship here compared to other big chain stores. We have relationships, we know our customers names, their partner, where their kids go to school, what’s going on at the farm. They’re not scared to talk to us, and they know it stays between us”.   Rex also noticed people struggling. “There was a greater need.” he says, “We saw people were struggling on a large scale, and not just our customers. People in many local businesses were having a tough time. Others we spoke to were seeing it too.” Rex recounts one conversation in particular with Steve Allen, Chairman at Tatua factory across the road from the store. “Steve came over one day to see Theresa for a trailer load of mag. She was talking to him outside and he was asking about how the farmers are and how things are going. What stood out was the real empathy he had for people. So, Theresa and I thought we’d talk to Steve about doing something.”  Two weeks after their initial chat with Steve, Rex and Theresa met again with Steve and Brendan Greaney, CEO of Tatua Dairy Company, Kathy Paton, Brendan’s PA, Wanda Leadbeater, Coordinator at Rural Support Waikato and Neil Bateup, Chairperson of Rural Support Waikato, to see what they could do to support local farmers in the Haruaki Plains, Morrinsville,  Matamata and Te Aroha areas. By the time the group held their second meeting, they saw the need for an event that could draw people from far and wide. Theresa recalls, ”At first, we were looking just to target farmers, rather than growers. At the second meeting we changed it to anyone dealing with the rural community. I’d recently had a horse dentist come in to do my horse’s teeth and she talked about pressure on vets. So, we decided we needed to maximise attendance.”  “We wanted anyone to feel they could come, and not have people think it was just for PGG Wrightson customers. The timing was important too, we wanted it to be at a time when people could attend, not at a time they were busy on-farm. It was ideal to have Rural Support as the main face of the event, as they are nationwide and have all the professional systems and processes in place to support people. RS had councillors on hand at the event too. It’s a lot easier to talk to someone when you meet face to face”.   The event drew over 500 people from Te Aroha to Bay of Plenty, with over a third of the attendees travelling over 50kms to attend. Rex and Theresa greeted every attendee at the door and invited them to enjoy the tables laden with steaks provided at no cost by local meat company, Greenlea Premier Meats. The meal was combined with a warm welcome from Steve Allen, followed by an introduction from Neil Bateup of the ever inspiring  JK himself. The highlight of the night was JK’s presentation, as one attendee described later, “JK just blew us all away with his helpful, informative amusing and totally entertaining hour or so.”  Rex recounts the generosity of the local businesses and community groups that supported the event. “The local support we received was outstanding. Stu and the Morrinsville Lions Club worked one of the three the BBQs, and they set up all the tables to a restaurant quality which made the dining very streamlined. Our local supermarkets, New World Morrinsville and Matamata, and PaknSave Thames provided volumes of bread rolls and salad. We thought we’d approach a few of the big accounting firms for support, but one chat to the team at Cooper Aitken was all that was needed. The team jumped on board and Vanessa joined the working group. Everyone who came on board contributed to the success of the event”. Over the hour, JK explained how he rolls out his day and

An evening with John Kirwan Read More »

Scroll to Top