News Articles

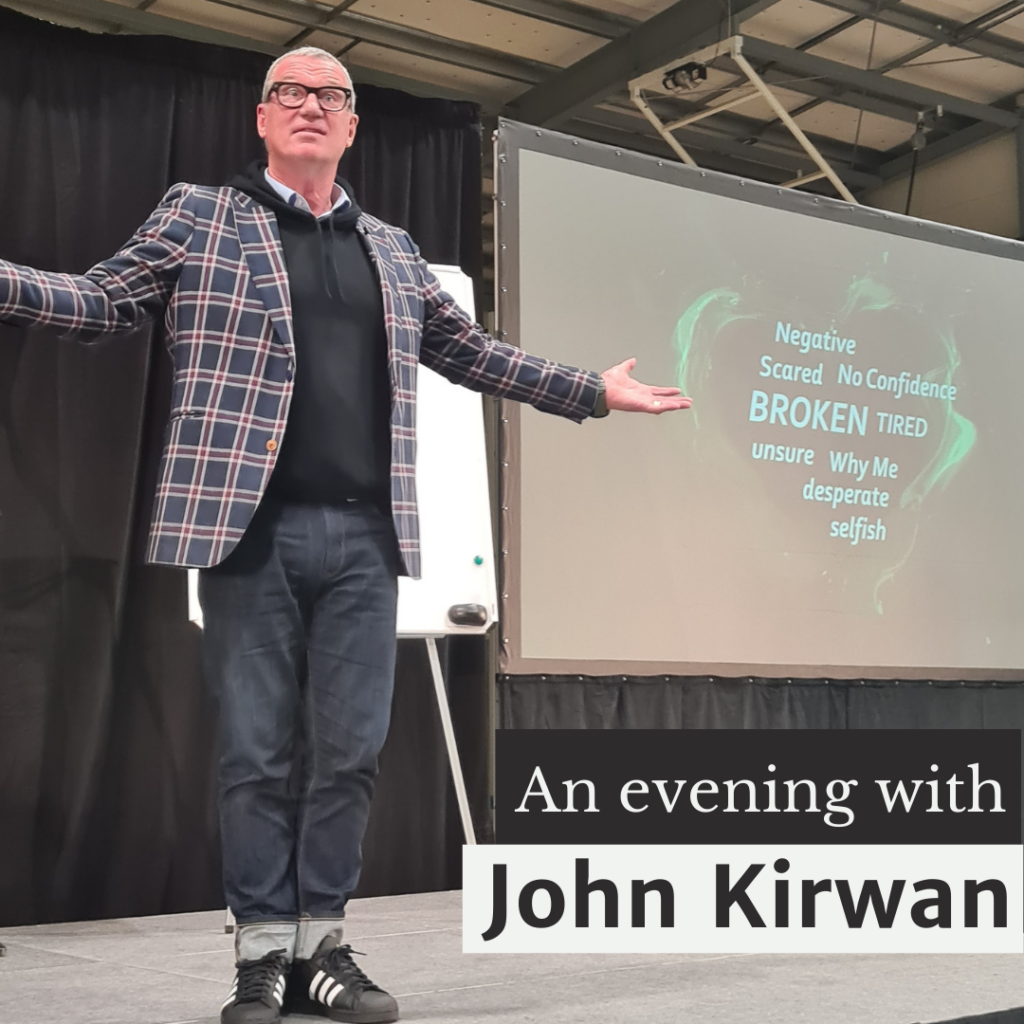
An evening with John Kirwan

Over 500 people gathered in Te Aroha last month to listen to Sir John Kirwan, or JK as he’s most commonly known, share his humble yet powerful words on managing mental health and the process of moving from surviving to thriving.  It was an important message for rural communities. Across the country there is a common theme emerging of people on farms who, over the past few years, have persevered through challenge upon challenge. Over time, this feeling of facing a battle on many fronts takes a toll. The result is once lively people looking weary, worn down and having lost their spark. This was apparent to Theresa Tomkinson and Rex Madden, who work together at PGG Wrightson Tatuanui.   Theresa has an eye for spotting when things are off with someone. As the saying goes, it takes one to know one. Recently Theresa has experienced the loss of her brother in December last year and dealt with her dog being run over. She also experienced a reaction to a COVID vaccine and had to deal with the stress of COVID vaccine mandates earlier in the year. As a result of all this Theresa had started having panic attacks. She knew she wasn’t okay and decided to have a chat to Rex, Store Manager at PGG Tatuanui.  While many well-meaning managers can inadvertently foster a culture of productivity first, people second, Rex is a bit different. As Theresa explains. “Rex is really open. It’s really good to have a boss you can talk to when things build up”. Thoughtfully, she adds “But the relationship needs to be there to start with. Bosses need to be approachable, and you need to know that they care.” Having reached out, and with Rex’s support at work, Theresa tried some different avenues and eventually found the professional assistance she needed.   Over the next few months Theresa’s wellbeing returned, but she started noticing the wellbeing of customers coming in. Farmers who had gone through drought and other challenges, who, while normally very happy, were not ok.  She says, “We’re a retail store, but it’s a different kind of relationship here compared to other big chain stores. We have relationships, we know our customers names, their partner, where their kids go to school, what’s going on at the farm. They’re not scared to talk to us, and they know it stays between us”.   Rex also noticed people struggling. “There was a greater need.” he says, “We saw people were struggling on a large scale, and not just our customers. People in many local businesses were having a tough time. Others we spoke to were seeing it too.” Rex recounts one conversation in particular with Steve Allen, Chairman at Tatua factory across the road from the store. “Steve came over one day to see Theresa for a trailer load of mag. She was talking to him outside and he was asking about how the farmers are and how things are going. What stood out was the real empathy he had for people. So, Theresa and I thought we’d talk to Steve about doing something.”  Two weeks after their initial chat with Steve, Rex and Theresa met again with Steve and Brendan Greaney, CEO of Tatua Dairy Company, Kathy Paton, Brendan’s PA, Wanda Leadbeater, Coordinator at Rural Support Waikato and Neil Bateup, Chairperson of Rural Support Waikato, to see what they could do to support local farmers in the Haruaki Plains, Morrinsville,  Matamata and Te Aroha areas. By the time the group held their second meeting, they saw the need for an event that could draw people from far and wide. Theresa recalls, ”At first, we were looking just to target farmers, rather than growers. At the second meeting we changed it to anyone dealing with the rural community. I’d recently had a horse dentist come in to do my horse’s teeth and she talked about pressure on vets. So, we decided we needed to maximise attendance.”  “We wanted anyone to feel they could come, and not have people think it was just for PGG Wrightson customers. The timing was important too, we wanted it to be at a time when people could attend, not at a time they were busy on-farm. It was ideal to have Rural Support as the main face of the event, as they are nationwide and have all the professional systems and processes in place to support people. RS had councillors on hand at the event too. It’s a lot easier to talk to someone when you meet face to face”.   The event drew over 500 people from Te Aroha to Bay of Plenty, with over a third of the attendees travelling over 50kms to attend. Rex and Theresa greeted every attendee at the door and invited them to enjoy the tables laden with steaks provided at no cost by local meat company, Greenlea Premier Meats. The meal was combined with a warm welcome from Steve Allen, followed by an introduction from Neil Bateup of the ever inspiring  JK himself. The highlight of the night was JK’s presentation, as one attendee described later, “JK just blew us all away with his helpful, informative amusing and totally entertaining hour or so.”  Rex recounts the generosity of the local businesses and community groups that supported the event. “The local support we received was outstanding. Stu and the Morrinsville Lions Club worked one of the three the BBQs, and they set up all the tables to a restaurant quality which made the dining very streamlined. Our local supermarkets, New World Morrinsville and Matamata, and PaknSave Thames provided volumes of bread rolls and salad. We thought we’d approach a few of the big accounting firms for support, but one chat to the team at Cooper Aitken was all that was needed. The team jumped on board and Vanessa joined the working group. Everyone who came on board contributed to the success of the event”. Over the hour, JK explained how he rolls out his day and

An evening with John Kirwan Read More »
Keeping your business cash liquid

As a business owner the main goal is to make a profit. To make enough sales at a big enough margin to generate a profit from your business.  It can be very common for any business owner to make a profit but then have issues with cash flow. Often business owners are confused as to why they made a large profit but have no money in the bank. Simply put, your profit is what you are taxed on at the end of the financial year. It’s the income left once you have paid all your expenses and suppliers  (does not include debt repayment). Whereas your cashflow is what is in your bank account as money comes in and out of the business on a daily basis.   An example of how profit and cash are different is Debtors – the people that owe you money. When you invoice a debtor, you add that to your sales and therefore your profit, and you pay tax on this. However, until they pay for the service, you don’t get the cash into the business. Therefore, managing debtors is one of the many key functions in managing the cashflow of your business. Without an even and predictable flow of cash into a company, you can’t cover your overheads, pay your employees, or run day to day operations – let  alone, considering growth for the business.  Essentially, profit can mean nothing if you haven’t got the cash flow to keep you going. It is the lifeblood of any business. In both commercial and agri industries we often see businesses caught in the cycle of growing sales and chasing or increasing milk production, however very few stop to review their profit margins. At the end of the day, you can make as many sales and kgs of milk as you like but if there is no profit margin, there is no profit and if there is no profit there is never going to be any cash. One simple way to start the ball rolling on improving profit margin is to consider setting or reviewing your KPIs or key performance indicators. These are like your dashboard on your car. It tells you how fast or slow you are going, whether you have enough fuel, oil and water. It gives you an indication about whether you’ll make it to your destination. It’s the same in business. Your dashboard in business are your KPIs essentially, they are the things that will tell you if you are on or off track in relation to your plan.   Some important KPIs can include; Commercial Gross profit percentage Debtor days Dairy Farming Profit per ha Farm working expense per kg As we head into the end of 2022, it is a time for reflection. How much profit did I make? How much cash did I generate this year? Projecting your cashflow pipeline over the next 12-18 months is vital in the current business environment to take the appropriate action to safeguard your cash position. You can’t fix a problem if you don’t see it coming.  A cashflow forecast allows you to plot inbound and outbound payments monthly so you can better predict what will be in the bank at the end of each month. Whether you are new to running a business or a seasoned owner who needs some financial support, we can give you the cash flow advice you need. We’ll review your finances, delve deep into cashflow and come up with key ways to increase cash income and reduce expenses. It only takes a few small changes to achieve a far better cash flow position for your business to help you maintain positive cash flow and generate meaningful profits.   Get in touch with us for a Cashflow Improvement Meeting. Amy Watson (Coombes)Partner, CA P: 07 889 7153E: amyc@cooperaitken.co.nzM: 027 715 2728 More on amy

Keeping your business cash liquid Read More »

October 2022

INCLUDED THIS MONTH; We say goodbye to Julie Congratulations to Megan Potter Read of the month – The power of cash flow forecasts Noticeboard Careers with CooperAitken download here

October 2022 Read More »

The power of cash flow forecasts

At some point in it’s lifetime, every small business suffers from cash flow problems. The trick is to think ahead and figure out when these problems are going to arise, so you don’t have to unexpectedly postpone a purchase or hurriedly seek out additional finance. This is where cash flow forecasts come in. To effectively manage your cash flow, essentially you use your sales and expenses figures to calculate your cash flow figures before they happen. Then you can plan to limit the impact of a cash drought before it arrives, so you can still pay your staff, the bank and your suppliers. The importance of cash flow forecasts Cash flow forecasts are used to predict your business’s future financial position for the period ahead, from three months to a year in advance. Your forecast allows you to see what money you expect to be paid into the business and the amount you’ll need to pay out. It’s a useful tool to help you manage your business more effectively. If we used a typical retail store as an example, you may see high sales over Christmas, and then a traditional slump after the New Year Sales, your cash flow forecasts would show high income in December and much lower income over the following two months. Your forecasts would also show stock purchased on a 30 or 60-day term ahead of the festive Christmas rush in November and December would need to be paid at the end of January and February. If you racked up record Christmas sales, there might be a strong temptation to splash out and buy that big-ticket item you’ve been dreaming of – but can you really afford it? A quick look at your cash flow forecast will probably tell you that you need to park the thought of a new car or holiday, reduce your drawings and hold on that big spend for now. Otherwise, you’ll have no money left to pay for the stock you sold in December. If you’re more pragmatic and less inclined to impulse spending, your forecast will also be able to tell you if you’ll generate enough profit to cover the costs of new refurbishments or hiring a new team member. Say your forecast sales figures for March and April will be down on previous years, as a result of continued low national economic growth, the global financial turmoil or the arrival of a new competitor in the market. You might need to arrange short-term finance to tide you over or find ways to increase sales to cover your monthly overheads and operating costs. In summary, your cash flow forecast gives you a future view into your business finances. It helps you identify cash flow problems before they appear and allows you to make informed business decisions. Putting your forecasts to use Apart from giving you a fairly good indication of your likely cash position at any point in time in the year ahead and alerting you to potential cash flow problems (which enables you to act in advance, rather than react), your cash flow forecasts can be used to model your future plans. Once you have your forecasts set up, you can use them to model “what if” questions about your business to help you make the best decisions for your business. If you need some support with your cash flow, talk to our team. get in touch

The power of cash flow forecasts Read More »

Could your business survive without you?

Would your business still thrive, or would it suffer a catastrophic failure if you suddenly stepped away? It’s tough to remove yourself from the day-to-day operations when you’re passionate and busy. However sudden accidents, illnesses, or family emergencies can – and will – happen and you need to be able to step back knowing your systems are robust enough to cope. For your business to work for you, you need to make yourself replaceable. Large corporations have plans in place to mitigate what’s known as ‘Key Man Risk’. But when you run a small business, who is the backup?  The more you can train and empower your team to perform the business’s essential daily functions without micromanagement, the closer you’ll be able to enjoy a lifestyle business. Establish repeatable and scalable support infrastructure to run the daily operations and create a great team that you can lean on. Your staff need a common purpose – knowing why what they’re doing matters – as well as clear expectations around their roles. By creating a suitable work environment, where employees both individually and as a team are more efficient and likely to enjoy what they do, you’ll breathe easier knowing they have your back (and your business) in an emergency. Finally, it’s important to know what the business looks like without you. An exit strategy is often thought of as the way to end a business — which it can be — but in best practice, it’s a plan that moves a business toward long-term goals and allows a smooth transition to a new phase. That may involve re-imagining business direction or leadership, keeping financially sustainable, or pivoting for challenges. Top Tips: No one is irreplaceable – Challenge yourself to step away for a week. Which systems fall over? Which procedures get left hanging? Which duties get ignored? Go cold turkey as a test case for the time you may have to leave your business in the hands of others.Embrace innovation – Get systems that are simple, streamlined, effective and can be used by multiple key team members. Make sure anyone can log in and see exactly what’s needed for what reason at any time.Recognise the value you’re creating – A business that doesn’t rely on its owner is worth a lot more when the time comes to sell or pass the reins to someone else. Strong plans and systems recognise the true value of a business and provide a foundation for future goals and new directions, so if you want some help putting together solid business plans and systems, get in touch with our team. get in touch

Could your business survive without you? Read More »

New Invoice Payment Options

We are committed to finding innovative ways to improve the way we do business with you.  As part of our ongoing development, CooperAitken is enhancing our systems and procedures.  Going forward, you will notice changes to how our invoices look and in the way we communicate with you about your account with us. Where you prefer to receive an electronic statement, these will now be emailed to you along with the copy of the invoice. We also now offer more options for you to pay your invoices: Internet banking Monthly Instalments – subject to credit criteria Credit Card – we now offer payment by Visa or Mastercard online Other Options – please contact our credit team as below for other payment options: Hazel Miller     hazel@cooperaitken.co.nz     027 262 5962 Ali Little            ali@cooperaitken.co.nz          027 212 2866  To pay online, head over to our payments page or click on the link at the bottom of your invoice. Another change you may notice is during the month when we are completing different pieces of work, we will invoice each piece of work when it’s completed rather than at month end.  Overall, the total fee will be the same and summarised on our statement. If you have any questions around our new systems, please do not hesitate to contact our office. make a payment

New Invoice Payment Options Read More »

September 2022

INCLUDED THIS MONTH; Read of the month – Could your business survive without you? Certificate of Public Practice – Congrats Chloe, Gerrie & Sharlotte Upcoming Sir John Kirwan Event The end of Banklink NZ Dairy Industry Awards Careers with CooperAitken Proud to Support download here

September 2022 Read More »

July | August 2022

INCLUDED THIS MONTH; New Trust Disclosure Rules: What you need to know, by Gerrie Jacobs Chartered Accountants ANZ team achievements Team News Quiz & Cocktail Team Night Careers with CooperAitken Proud to Support download here

July | August 2022 Read More »

New Trust Disclosure Rules: What you need to know

The 2020/2021 year will always be remembered for the worldwide Covid-19 Pandemic which affected people from all walks of life. Whilst the virus was slowly spreading two significant tax changes happened in New Zealand, specifically: The Government proposed new trust disclosure rules and passed it into law five days later with little to no consultation, almost as if by stealth The Government also passed legislation under urgency to increase the top individual income tax rate from 33% to 39% for personal income in excess of $180,000 Both changes are applicable from 1 April 2021. The Government’s motivation behind the new disclosure rules has a direct correlation to the use of a trust as a tax planning tool. The new rules will enable Inland Revenue to establish to what extent trusts are used to effectively avoid the 39% tax bracket. The new rules will additionally enable the Inland Revenue to share the disclosed information with overseas tax authorities and other New Zealand Government Departments such as the Ministry of Social Development. What do the New Disclosure Rules entail? In short, from the 2021 – 2022 income year  all New Zealand Trusts  have to: Disclose a laundry list of additional information Prepare financial statements File a tax return Complying Trusts that are non-active with interests only income of less than $200 per annum are exempt from the above three requirements. Per Inland Revenue legislation the additional information is provided with the IR6 Trust Tax Return in the form of: IR6S – Relates to Settlor & Settlements (Current Year Settlements) IR6B – Relates to Beneficiaries details IR6P – Relates to the details of any person that has the power to appoint or dismiss a trustee, to add or remove a beneficiary, or to amend the trust deed The additional information required to furnish the above forms include but is not limited to: The amount of settlements made to the trust in the income year which includes cash, financial arrangements, land, buildings, shares/ownership interest and settlements that have been valued at zero. The full name, date of birth, jurisdiction of tax residency and IRD number or Tax Identification Number (if tax resident in another country) of all settlors. The full name, date of birth, jurisdiction of tax residency and IRD number or Tax Identification Number (if tax resident in another country) of all beneficiaries as well as any movements in beneficiary current accounts which include: The Opening balance Distributions (accounting income, trust settlement, capital, use of trust property for less than market value, distribution of trust assets and forgiveness of debt) Amounts withdrawn or enjoyed from the trust The Closing balance of the amount owed to the beneficiary or owed to the trust Over and above the non-active trusts that are exempt of the new rules, the following trusts are also exempt: Estates still under administration Foreign Trusts Charitable Trusts Trusts that are eligible to be Maori Authorities Widely-held superannuation funds Exempt employee share scheme Debt funding special purpose Lines Trusts How does it affect you? Trustees have to spend more time than ever before on the administration of a trusts, it is also likely that there will be a large increase in the compliance cost for trusts because a lot of the information required by the new rules is not always readily available. We are finding that the 2022 year is particularly challenging as all of the required information not only has to be sourced, it also needs to be entered into the prescribed Inland Revenue provided IR6 returns. Income tested benefits you receive may be affected in that Inland Revenue will now have access to not only taxable income distributions but also non-taxable distributions which are both taken into account for testing purposes. An example being working for families. Inland Revenue has the power to request the same information from the trust for the previous eight years should they find anything of concern during their review of the 2022 income tax returns as filed. In summary we believe the impact of the new disclosure rules are significant on trustees and we urge you to contact us if you would like to discuss your trust disclosure obligations. download a copy Gerrie JacobsAssociate, CA P: 07 889 7153E: gerrie@cooperaitken.co.nzM: 021 284 6444

New Trust Disclosure Rules: What you need to know Read More »

May | June 2022

INCLUDED THIS MONTH; Did Dairy Farmers actually make a big profit in 2022? By Coral Phillips 2022 Herd Scheme Values Directors Strategic Retreat Law change for incorporated societies Matamata office Proud to Support download here

May | June 2022 Read More »

Scroll to Top